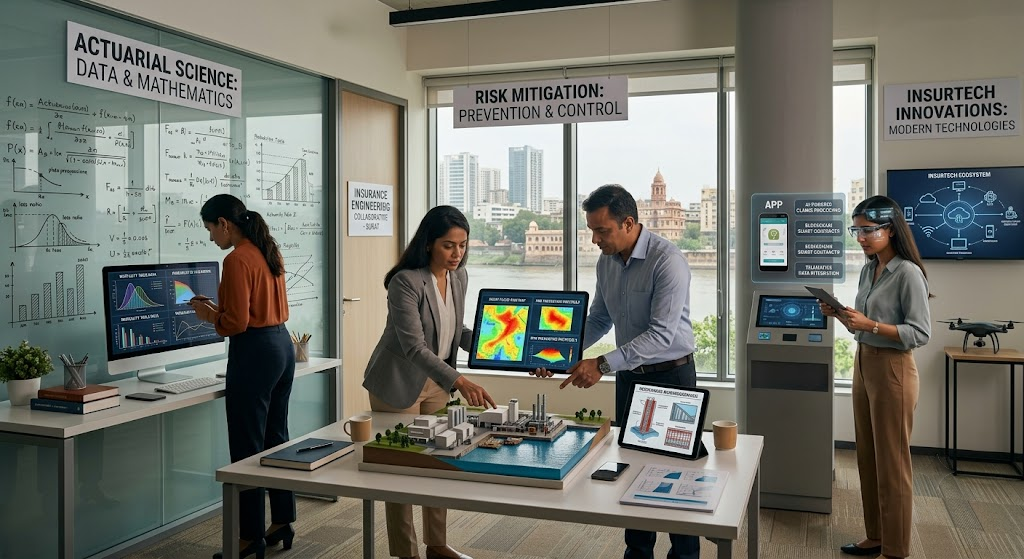
Insurance provides an essential financial risk-mitigation framework within modern economies, protecting individuals, commercial enterprises, and public infrastructure against unexpected loss events. By pooling independent risks using actuarial probability modeling and statistical analysis, insurance structures turn potentially devastating financial events into manageable, predictable operational costs.
1. Principles of Actuarial Science and Risk Pooling
Insurance operates through mathematical statistics, financial theory, and actuarial analysis to calculate potential risk exposures across large groups of policyholders.
Fundamental Legal and Financial Principles
- Principle of Indemnity: Insurance contracts are designed to restore an insured party to their pre-loss financial position following an approved claim. Insurance cannot be structured to allow an insured party to profit from a loss event.
- Principle of Utmost Good Faith: Both the policy applicant and the insurance provider are legally bound to fully disclose all material risk facts accurately. Intentionally concealing relevant details can render a policy contract invalid.
- Principle of Insurable Interest: An entity can purchase insurance only on assets or individuals where they hold a legitimate financial interest, meaning they would suffer direct financial loss if damage or injury occurs.
- The Law of Large Numbers: By pooling a large volume of similar risk exposures, actuaries can accurately predict aggregate claim frequencies across population groups, allowing for accurate premium pricing.
2. Core Insurance Sectors and Asset Protection
Modern risk engineering spans four primary insurance domains:
Life Insurance and Capital Protection
Life insurance solutions protect surviving beneficiaries against the loss of household income following the policyholder’s death. Coverage ranges from pure risk protection (Term Life) to hybrid structures that combine risk coverage with long-term savings components.
Health and Medical Insurance
Health coverage offsets expenses arising from medical consultations, emergency hospitalizations, specialized surgical procedures, and prescription medications. Modern policies incorporate preventative wellness initiatives alongside catastrophic illness protection.
Property and Casualty (P&C) Insurance
Property and casualty insurance protects physical assets—including residential properties, commercial real estate, vehicles, and industrial machinery—against physical damage caused by natural disasters, fires, theft, or operational accidents.
Commercial Liability and Cyber Risk Coverage
Commercial liability protects businesses from third-party legal claims, product performance liabilities, and professional errors. A rapidly growing segment, cyber liability insurance covers financial losses resulting from corporate data breaches, ransomware disruptions, and associated legal liabilities.
3. The Digital Transformation of Underwriting and Claims
Technology is modernizing traditional insurance workflows into dynamic, real-time analytics platforms.
Artificial Intelligence in Underwriting
Traditional underwriting relied on static historical health or financial questionnaires. Contemporary InsurTech systems utilize machine learning models to analyze continuous data streams—such as wearable fitness device logs, connected home sensor alerts, or satellite imagery—to evaluate risks faster and dynamically price policies.
Telematics and Usage-Based Insurance (UBI)
In auto and commercial fleet insurance, IoT telematics devices record real-time operational data including vehicle speeds, braking intensity, driving hours, and cornering stability. Insurers utilize these metrics to offer usage-based pricing discounts to drivers who maintain safe driving profiles.
Automated Claims Processing Pipelines
Modern claims platforms integrate Optical Character Recognition, computer vision algorithms, and automated fraud-detection engines to process claims quickly. Policyholders can upload damage photos via mobile applications, triggering automated damage assessments, repair cost calculations, and direct electronic claim payouts.
4. Key Insurance Terms and Coverage Considerations
Understanding specific insurance policy terms is critical when evaluating coverage frameworks:
- Policy Premium: The recurring payment required to maintain active insurance coverage.
- Deductible: The initial out-of-pocket loss amount that a policyholder must pay before their insurance policy begins covering remaining costs.
- Co-Payment: A fixed, flat fee paid by a policyholder at the time a specific medical or technical service is rendered.
- Coverage Cap / Policy Limit: The maximum financial benefit amount an insurer will pay out under a policy contract for a covered event.
5. Frequently Asked Questions
- What is the difference between a policy deductible and a co-pay?A deductible is a fixed annual dollar amount a policyholder must pay out of pocket before the insurer begins covering expenses. A co-pay is a fixed fee paid at the time of a specific service, such as a doctor’s visit or prescription pick-up, even after the deductible has been met.
- What is Reinsurance, and why is it important for financial stability?Reinsurance is insurance purchased by primary insurance companies to manage their own risk exposure. By transferring portions of their risk portfolios to global reinsurers, primary insurers protect their capital solvency against major catastrophic events like severe natural disasters.
- How do pre-existing conditions affect health insurance underwriting?Pre-existing conditions represent known health conditions requiring ongoing medical care. Health insurance regulations often govern how pre-existing conditions are covered, sometimes using waiting periods or community rating systems to ensure broad, fair access to coverage.